The power system in the Blockchain industry: from the origins to the resistance
The phenomenon inevitably recalls what happened during the dot-com bubble of the late nineties, when thousands of internet-related companies sprang up practically overnight promising to transform the global economy. Then, as now with blockchain, a futuristic story, a website and the feeling of taking part in a historic revolution were enough to attract millions of dollars and reach gigantic valuations.
At that time, search engines, web portals, online stores and technology companies appeared that seemed destined to dominate the future. Many disappeared a few years later. However, the internet did end up transforming the planet. It changed the economy, the media, advertising, commerce and the way people relate to each other.
Market cleansing phase
And perhaps that is where the parallel with the current state of the crypto market appears. Most blockchain projects may not survive, just as most dot-com companies did not survive. But that does not necessarily mean the technology will fail. It may mean that the market is entering a cleansing phase where only a few infrastructures will end up consolidating as pillars of the digital financial future.
While media attention and liquidity increasingly concentrate around Bitcoin, Ethereum or Solana, dozens of projects are silently disappearing from the map. Some lose volume and community, others stop being listed on major platforms and many continue to operate technically, but become a kind of digital ghost town: networks active on paper, yet practically absent from the conversation and from the real flow of the market.
With the Clarity Act, Satoshi Nakamoto's technology enters Wall Street
Binance's recent decision to remove from its platform tokens such as Syscoin, launched in 2014, Enzyme — previously known as Melon Protocol and launched in 2016 —, Harvest Finance, one of the symbols of the 2020 DeFi explosion, Automata, presented in 2021 as privacy infrastructure for Web3, or Phoenix, linked to the new narratives of automation and decentralized artificial intelligence, is not merely a technical adjustment by the world's largest exchange.
Cleansing excesses
All of them were, at different points in the crypto cycle, projects considered innovative, promising or even capable of representing part of the future of blockchain. Some proposed new technical architectures, others tried to reinvent decentralized finance and others sought to build infrastructure for privacy, tokenization or digital automation.
But their gradual exit from the major markets reflects something much deeper than a simple technical adjustment. The crypto ecosystem is beginning to cleanse its excesses, just as happened with the internet after the dot-com bubble burst. Liquidity, attention and users are starting to concentrate around an ever smaller number of dominant networks, narratives and platforms, while hundreds of projects are trapped in a slow, silent disappearance. Because perhaps cryptocurrencies have just entered their own year 2000, when the internet seemed infinite.
In the late nineties, the internet promised to change the world and, for the first time, it seemed possible to invest directly in that future. The network was beginning to expand at an unknown speed and millions of people felt they were witnessing the birth of a new economic, technological and cultural era.
Thousands of startups were born practically overnight. Online stores, search engines, web portals, content platforms, digital advertising companies and projects appeared that, in many cases, barely had a defined business model, but did have wonderful stories about how they would transform the future. Investors bought any company that added .com to its name.
Terra, the Spanish internet dream
The logic was that if the internet was going to transform the world, everything related to the internet had to be worth billions. And, in a way, they were right. The internet transformed the economy, the media, advertising, the way we relate to each other, commerce and practically every aspect of daily life. But what did not survive was most of the companies that promised to lead that transformation.
The crypto market buries the old blockchains: EOS, Dash and Tezos agonize
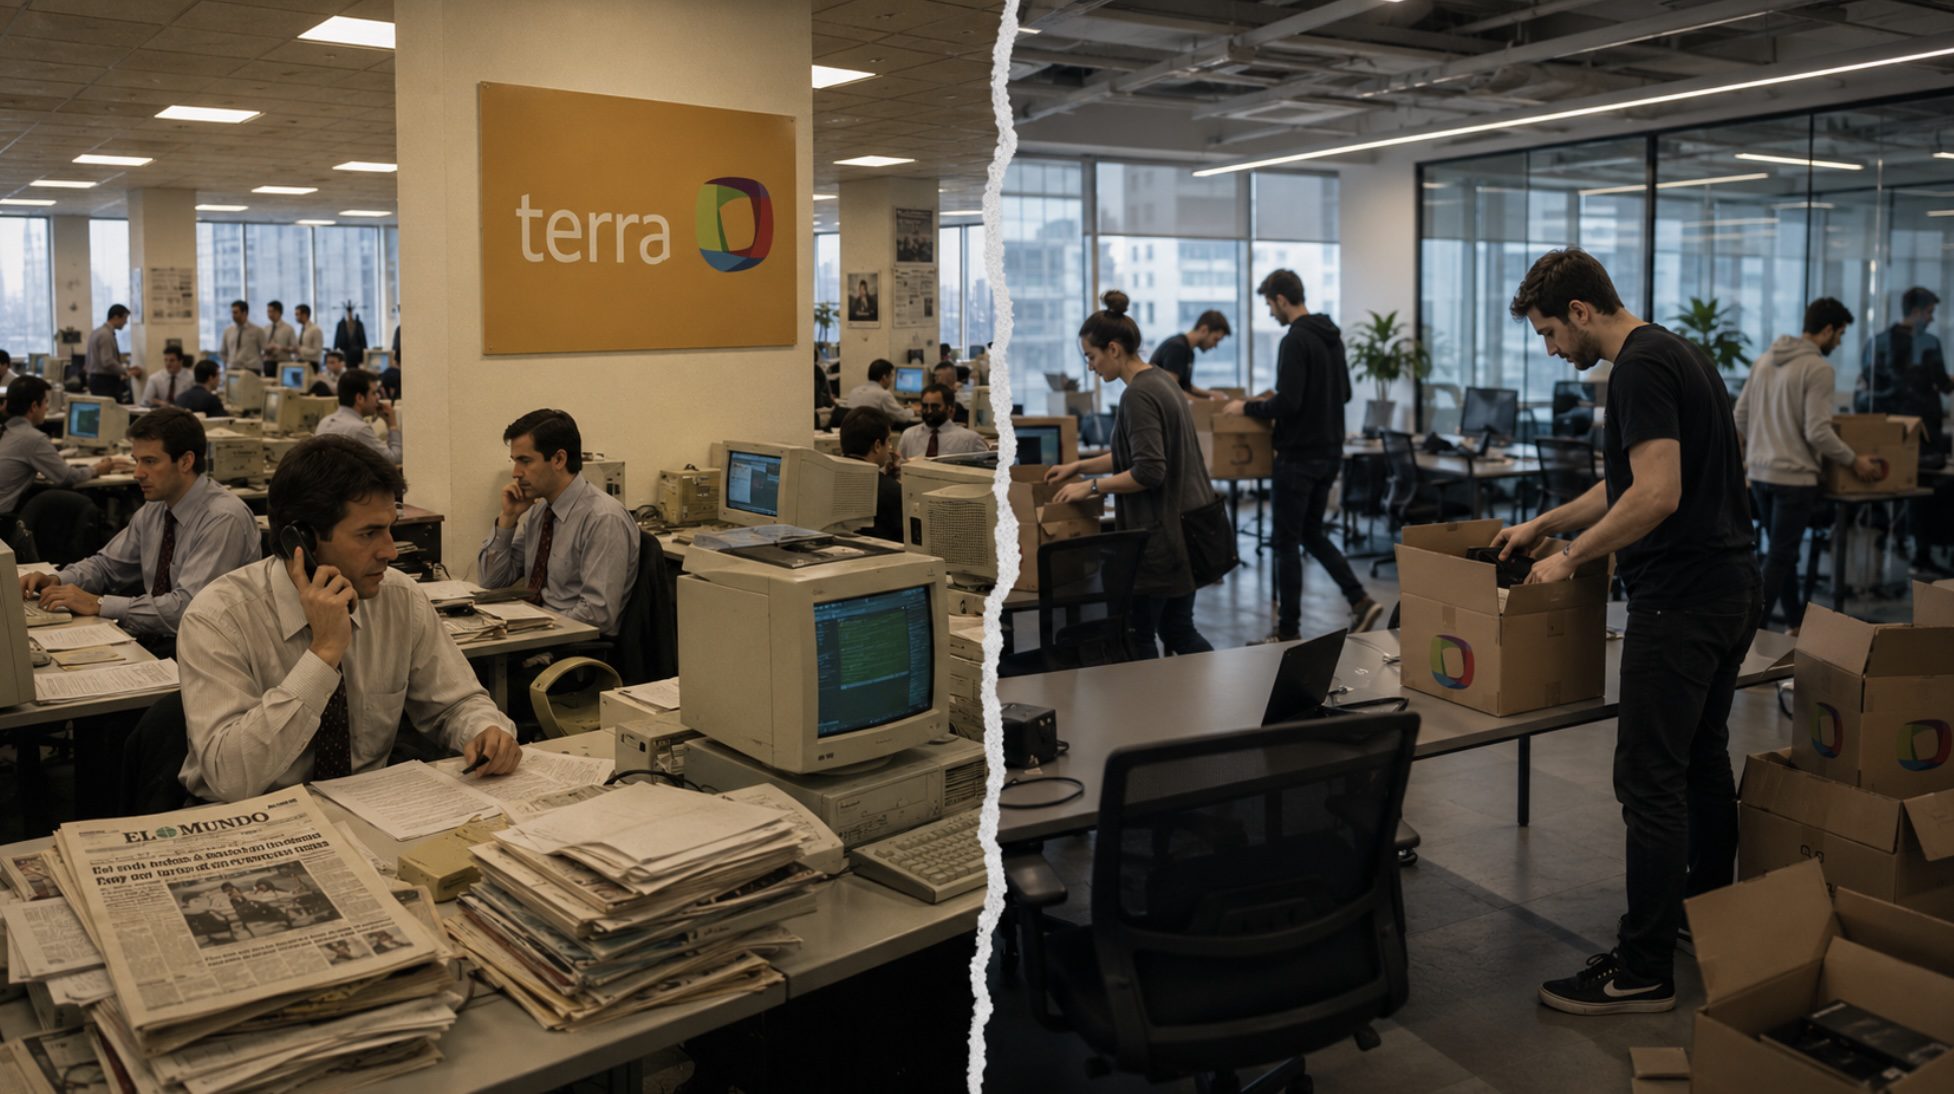
In Spain, no company better symbolizes that technology fever than Terra. The company was born in partnership with Telefónica, which understood that the internet was going to completely transform telecommunications, the media and the economy. In the late nineties, the feeling was that whoever controlled the gateway to the internet would end up controlling much of the digital future.
Telefónica gradually gathered different digital projects and existing online portals, among them Olé, one of the first major search engines in Spanish. And from that base it began to create the great internet portal of the Spanish-speaking world. Terra wanted to be practically everything at once: digital newspaper, search engine, email provider, online community, web directory, financial portal, entertainment platform and gateway to the internet for millions of users.
Terra came to be worth 37,000 million euros
At that time, before the explosion of Google, Facebook, YouTube or WhatsApp, browsing the internet often began from large portals like Terra. For millions of people, that home page was practically the entire internet.
The company aspired to concentrate the user's entire digital life in a single place. Seen from today's perspective, Terra looked like a mix between a digital newspaper, Yahoo, MSN, a social network and a search engine. The company's characteristic orange design ended up becoming one of the great visual icons of the early Spanish internet and a symbol of an era in which it seemed that Spain could build its own global technology giant.
When Terra went public on November 17, 1999, the company immediately became one of the great symbols of the technology fever sweeping the financial markets of the late nineties. According to information gathered by Cinco Días, demand for shares was so enormous that a lottery had to be held among small investors to allocate a maximum of 25 shares per person. Terra debuted at 11.81 euros and closed that same day at 37 euros, a rise of 184.61%.
How complexity devoured the Polkadot and Cosmos hyperchains
Thousands of small Spanish investors bought shares convinced they were entering the future. The share price continued to soar over the following months until it reached its all-time high on February 14, 2000, when the shares touched 157.6 euros. In just three months, the company had appreciated more than 1,000% and came to reach valuations close to 37,000 million euros.
The Lycos purchase: the climax of the bubble
It was an enormous figure for a company that still had no solid profits and whose business model was built much more on future expectations than on real results. But what the market really valued was the idea that whoever controlled the gateway to the network would end up controlling much of the 21st-century economy. For a few months it seemed that Spain was building its own European Google or Yahoo.
The most symbolic moment came in 2000, when Terra bought Lycos for about 12,500 million dollars. Lycos was then one of the world's great internet portals and competed directly with giants like Yahoo, MSN and the first major global search engines that were beginning to dominate the network. The deal aimed to create an international giant capable of dominating the Hispanic market and competing on equal terms with Silicon Valley. For a few months it seemed possible that a Spanish company could become one of the great global players of the internet. Shortly afterwards came the collapse.
In the United States, one of the great symbols of the dot-com bubble was Pets.com. The company sold pet food and accessories over the internet and perfectly represented the almost irrational enthusiasm surrounding any business related to the network. The idea seemed revolutionary and futuristic. The problem was that the company was losing money massively while spending fortunes on marketing, advertising and expansion.
Symptoms similar to those the internet experienced before the dot-com bust
During the dot-com bubble, financial imbalances barely seemed to worry the market. What mattered was growing fast, conquering users and conveying the feeling that the internet was going to generate infinite profits in the future. Valuations rose driven by gigantic expectations and by the idea that any company related to the network would end up dominating the global economy.
But when the money began to disappear and the market stopped rewarding promises alone, the collapse came. Many companies that seemed unstoppable sank within months and some, like Pets.com, ended up disappearing less than a year after going public.
Today, the crypto market is beginning to show symptoms very similar to those the internet experienced before the dot-com bubble burst. Between 2017 and 2022, thousands of projects related to ICOs, DeFi, NFTs, metaverses, memecoins, Layer 1, decentralized artificial intelligence and experimental financial protocols were born.
The role of crypto media
For years, practically any blockchain narrative managed to attract investment, community and media attention. Part of that news coverage was also built from specialized media closely linked to the crypto ecosystem itself. CoinDesk belonged for years to Digital Currency Group and was acquired in November 2023 by the exchange Bullish.
Decrypt was born linked to Consensys, one of the large software companies of the Ethereum ecosystem. The Block was embroiled in controversy after it was revealed that its CEO had received million-dollar loans from Alameda Research, the firm associated with FTX, and later ended up being acquired in the majority by Foresight Ventures, a fund specialized in digital assets. The firm acquired 80% of the newspaper for 60 million dollars.
Cointelegraph, one of the most influential crypto media in the world, also represents that complex relationship between information and the blockchain ecosystem. Unlike other major media in the sector, the company's shareholding structure and real ownership have never been especially transparent and, in practice, it is not clearly known who really controls the outlet. The outlet operates through various international structures and little publicly visible companies.
A deeply interconnected structure
The sector often worked as an economy where exchanges, funds, blockchains, influencers and specialized media jointly fed the feeling of building an inevitable revolution. Capital financed projects, projects boosted communities, exchanges listed tokens and specialized media constantly amplified new narratives about the future of the internet, finance and decentralization.
That does not necessarily mean an absence of critical journalism. In fact, CoinDesk was key to exposing the financial web of FTX and Alameda Research, which triggered one of the biggest collapses in crypto history. But that episode also laid bare the extent to which the ecosystem worked as a deeply interconnected structure, where media, funds, exchanges and large companies coexisted within complex relationships of competition, investment and narrative building.
When real liquidity problems, inflated balance sheets and opaque financial structures began to appear, even part of the media most integrated into the ecosystem ended up accelerating the rupture of the narrative that had sustained the market for years.
Ideas ahead of their time
Many of those projects were technically interesting and some even proposed ideas ahead of their time. However, the market is now beginning to harden and the speculative logic that drove the massive growth of altcoins is starting to change. Investors no longer ask only what technology a project has. Now they ask about real users, economic activity, liquidity, whether it complies with regulation or whether it will be able to survive in ten years. And that is where exchange delistings, abandonments and the silent disappearances currently sweeping the crypto ecosystem begin.
Likewise, some of the blockchains that for years made big headlines in specialized media are beginning to show clear signs of exhaustion. Projects like EOS, Tezos, Algorand, NEO or even Internet Computer came to be presented as infrastructures capable of competing with Ethereum or reinventing the internet and digital finance.
Most remain technically active, maintain foundations, developers and communities, but have lost the feeling of being inevitable in the market. Capital, liquidity and attention are now shifting toward much more concentrated ecosystems, while numerous blockchains are trapped in a kind of digital limbo, alive on paper, but increasingly far from the center of the market.
The arrival of institutional players
At the same time, the crypto industry is entering a new phase marked by the massive arrival of institutional players. Major banks, investment funds and asset managers are beginning to occupy the space that for years was dominated by crypto communities, independent developers and retail speculation.
The entry of giants like BlackRock, Fidelity Investments or Franklin Templeton through Bitcoin ETFs and tokenized financial products is profoundly transforming the market. At the same time, banks like JPMorgan Chase are developing their own blockchain infrastructures and tokenized payment systems, while entities like Banco Santander, BBVA or Société Générale offer crypto products and are making progress on issues related to custody, tokenization and services linked to digital assets.
The rise of stablecoins is also accelerating that institutional transformation. Companies like Circle and Tether already handle tens of billions of dollars, while banks and governments study how to integrate digital currencies within traditional financial infrastructure. Even payments giants like Visa and Mastercard are actively working on stablecoin-based networks and blockchain payments.
Regulations
To all this is added regulatory progress. Rules such as MiCA in Europe or future US legislation linked to CLARITY are pushing the market toward a much more regulated, professionalized and institutionalized environment. And that completely changes the rules of the game.
It is no longer enough to have an attractive narrative or an active community. Now liquidity, custody, transparency, regulatory compliance and the ability to integrate within the global financial system matter. Exactly as happened after the dot-com bust, when the internet stopped being only an experimental space and began to become critical economic infrastructure for the planet.
Amid all this transformation, it is striking that many of these digital deaths do not even generate big headlines. They simply happen. A token stops being listed, a Discord empties, developers abandon GitHub, liquidity disappears and the market keeps moving as if nothing had happened. Many blockchains remain technically active, but culturally they have ceased to exist for much of the ecosystem.
Around Bitcoin, Ethereum and Solana
Meanwhile, capital, developers and users increasingly concentrate around Bitcoin, Ethereum, Solana and a few dominant infrastructures. Exactly as happened after the dot-com bust, when the internet survived, but concentrated in a few giant platforms.
And yet, while many historic blockchains lose relevance, memecoins continue to absorb a huge part of the market's attention and speculation. Currently, the memecoin sector moves around 35,000 million dollars in market capitalization. Dogecoin alone concentrates close to 18,600 million dollars, while Shiba Inu is around 3,500 million and projects like Pepe, Bonk, Floki or dogwifhat continue to move hundreds of millions.
Today, they move a volume of more than 8,000 million dollars a day, a gigantic figure for assets whose value often depends more on virality and internet culture than on a specific technological utility. Memecoins are the last refuge of the pure speculative liquidity of the old crypto era, an ironic contrast with the sober institutionalization brought by BlackRock or JPMorgan.
The paradox of technology bubbles
However, history has shown that great technology bubbles tend to exaggerate the immediate value of an innovation, but not the historic change it ends up causing. The dot-com bubble exaggerated valuations, expectations and the speed with which digital companies would transform the economy. But the internet ended up changing the world in a way even deeper than many imagined at the time.
Perhaps blockchain is now entering that same cleansing phase. Most tokens may disappear, many blockchains may become irrelevant and hundreds of projects may end up forgotten in the immense digital graveyard of the crypto market. But that does not necessarily mean the technology has failed. Perhaps it means that blockchain is ceasing to be an experiment or a financial laboratory to begin becoming global infrastructure.
Tokenization, stablecoins, programmable payments, digital identity or onchain finance continue to advance silently while much of the speculation disappears. Just as happened after the dot-com bust, when hundreds of companies collapsed while the internet continued to expand throughout the global economy.
And while that transformation happens, the crypto market is beginning to look more and more like the Nasdaq of the year 2000, a place where thousands of technological dreams compete to survive knowing that probably only a few will end up becoming the dominant infrastructures of the future.