The on-chain lending market has once again attracted capital at institutional scale. Morpho closed a $175 million round with a16z, Paradigm and Ribbit Capital as lead investors, the largest operation in the sector so far in October. The figure is the news and it is also the least interesting part of the story.
What matters is what those funds are buying. Morpho competes in a market that seemed settled, that of crypto-collateralized lending, dominated by Aave and Compound. Its thesis is that liquidity should not sit in a single pool per asset, but in isolated, optimized markets that each user can create and parameterize, with capital efficiency as the argument.
The timing of the round is striking. It comes the same week that an oracle failure took $8.7 million from Moonwell and a third-party module drained 114 ether from Aave, and two weeks after this outlet published an assessment of restaking whose conclusion was that the fever had passed. Capital is not fleeing DeFi, it is choosing which part of DeFi to finance. The sector had come through two years in which capital went to rented security and incentive points, and the shift toward credit changes the map of who finances whom.
Morpho and why the funds like it
Morpho began as an optimization layer on top of Aave and Compound that directly matched lenders and borrowers when it found a match, and evolved into its own protocol with isolated markets. Each market has its own collateral, its own oracle, its own liquidation rate and its own limit, and anyone can create one by depositing collateral.
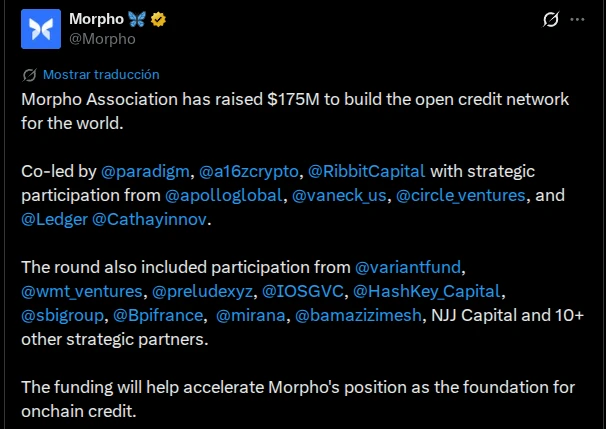
Morpho's announcement of the round on its X account
That design solves an old problem of shared pools: an exotic asset contaminates the risk of the entire pool, and the protocol's governance ends up deciding which collateral gets in and which does not. With isolated markets, risk is segmented and the protocol becomes neutral infrastructure, not an admissions committee.
The model also has an uncomfortable consequence. If anyone can create a market, the quality of the oracles and the parameters becomes the creator's responsibility, and failures multiply. The two incidents of the week point exactly to that.
The money coming in is not just for growth
A $175 million round in a lending protocol is explained by three needs. The first is regulatory: operating with institutions requires legal entities, audits and compliance teams that are not funded with tokens. The second is security: protocols with billions deposited now maintain permanent audit programs that cost millions a year.
The third is distribution. Large allocators, treasury funds and family office desks do not reach a smart contract on their own; they need an interface, support, reports and counterparties with a name. Building that layer is a people business, not a code business.
a16z and Paradigm have invested in almost every layer of crypto infrastructure and Ribbit comes from traditional fintech. The combination suggests a bet on credit as a category, not on a specific protocol: if yields on traditional deposits fall, on-chain collateralized lending becomes an alternative for corporate treasuries.
What is missing for on-chain credit to be a market
Crypto-collateralized lending works and is proven. Uncollateralized credit, which is 95% of real credit in the world, has still not solved the problem of identity and default. Several projects have attempted bridges with the traditional financial system and none has reached relevant volume.
Morpho's isolated markets allow a different approach: creating markets with real-world collateral, such as tokenized Treasury bills, with specific liquidation rules. That is the route through which tokenized debt funds are entering, and they already account for the majority of deposits in real-world asset lending.
The usual question about profitability remains. The interest rates DeFi pays are higher than bank rates because they include a risk premium that users accept and that in a cascading liquidation becomes a loss. Morpho's round does not change that arithmetic; it finances the infrastructure that should make it safer.
2027 will be the real test
The metric that matters is not total volume or value locked, which can be inflated with incentives. It is how much of that capital comes from institutions that repeat quarter after quarter and how much of the isolated markets survives when the risk premium narrows.
Morpho now has money for two years of building and a new responsibility: to prove that the risk segmentation it sells does not shift the problem onto the user who creates the market. If it succeeds, on-chain credit will have a genuine institutional layer.