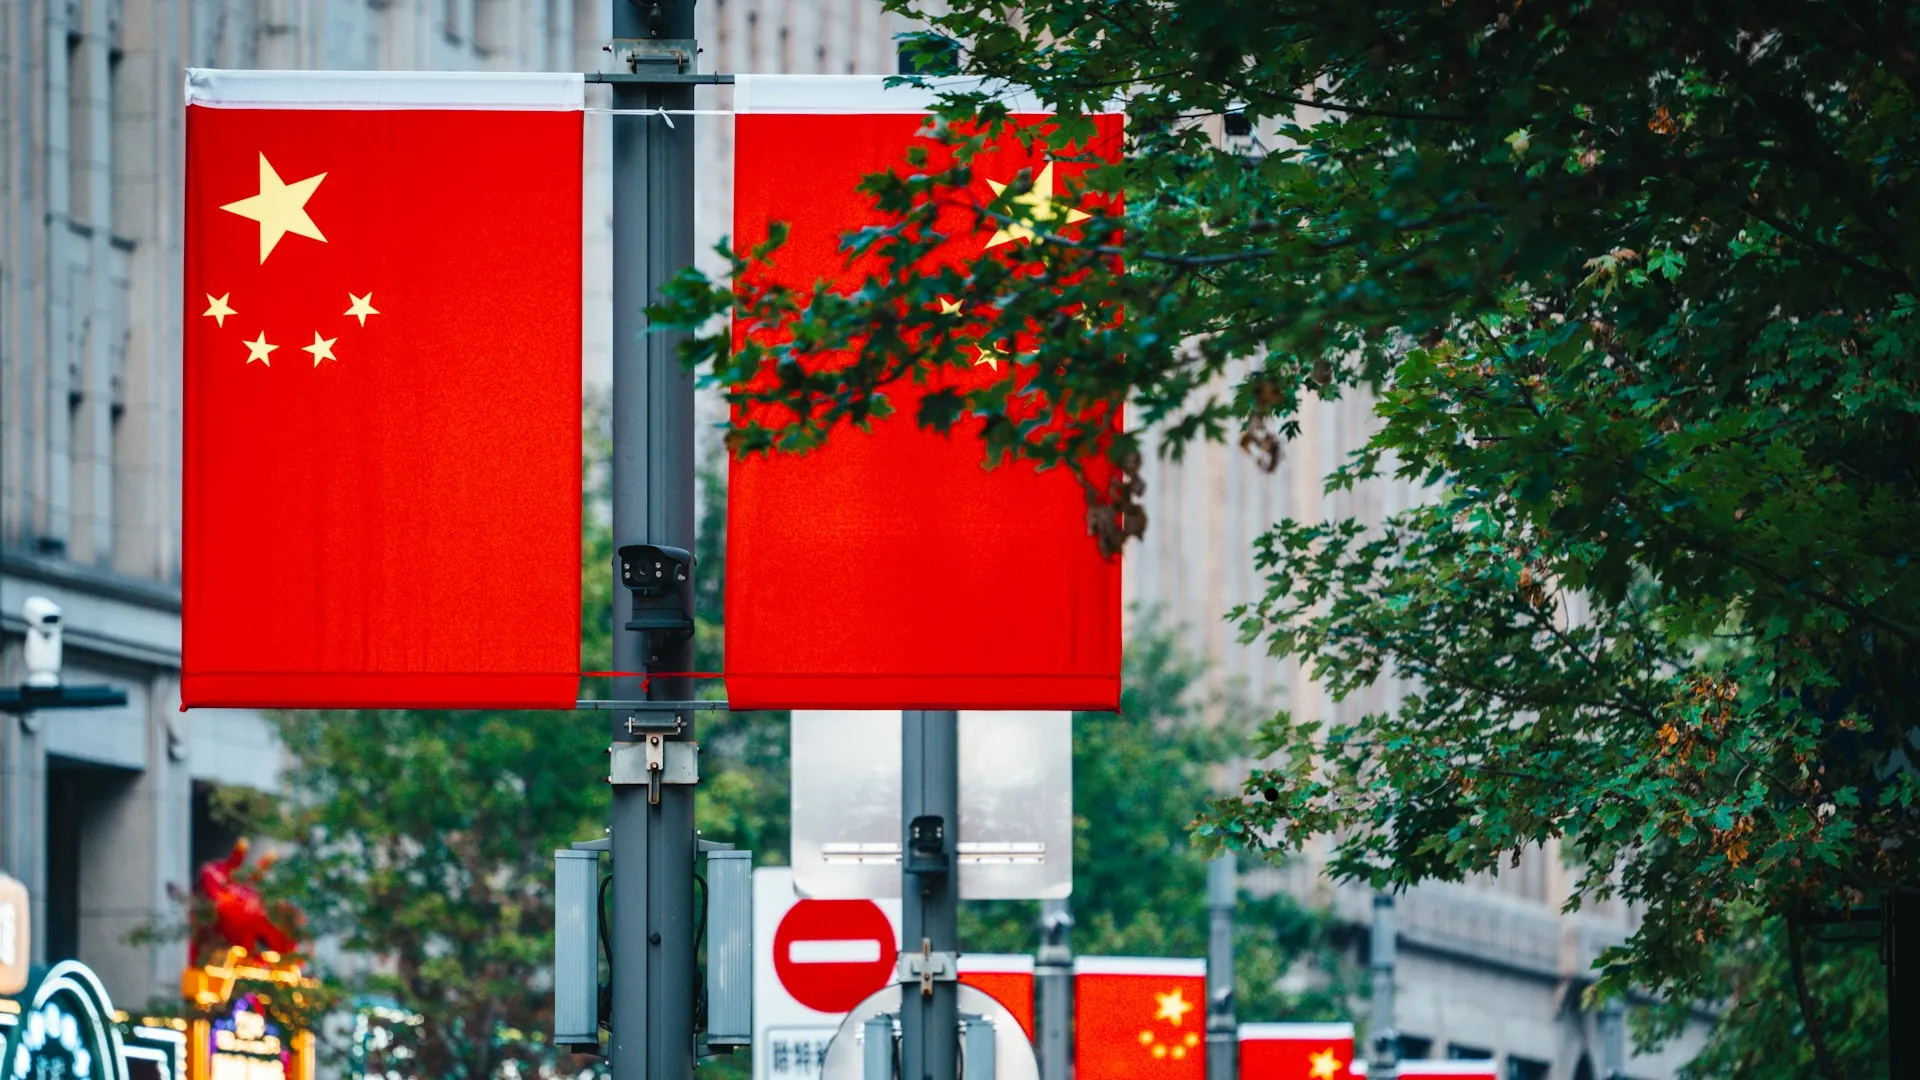
China is once again putting blockchain at the center of its industrial policy, and it is doing so without touching the red line it has maintained since 2021. The Central Committee of the Communist Party and the State Council published on October 9, 2026 a guideline document with 19 measures spread across five areas, and one of them is to build a national blockchain network. The text presents it alongside a national integrated computing power network, within a package that seeks to connect the real economy with the digital economy.
The label that organizes the entire document, "new quality productive forces," is Beijing jargon for what in Brussels we would call industrial policy with a technological accent. The plan lists quantum technologies, industrial biomanufacturing and hydrogen as a next-generation energy carrier, and adds an "AI+" program aimed at low-emission production. Blockchain enters there as a verification layer for the data markets the text also promises, with information property rights systems and pilot projects on data elements.
What does not appear in the 19 measures weighs as much as what does. The document does not mention bitcoin or ether, does not talk about stablecoins and does not refer to permissionless systems or trading activity. The 2021 ban remains in force, and a notice dated February 6, 2026 recalled that bitcoin, ether and tether are not legal tender in the country. That split, infrastructure yes and market no, is the key to reading the announcement without confusing it with an opening.
A network to connect what already exists
The text describes the network as infrastructure to link data systems and economic systems, with no more precision than that in the sectoral reading of the document published three days later. In its 19 measures there is nothing about cryptoassets, trading or payments with digital assets.
There is no investment figure, no construction timeline, no published technical architecture, not even a designated operator to launch it. The division of tasks is another missing piece: the Central Financial and Economic Affairs Commission and the National Development and Reform Commission (NDRC) appear as supervisors of the rollout, without the text assigning them specific functions.
The gap between what the plan orders and what it leaves open is better understood in columns, because the pieces the document does name arrive without the detail that whoever has to build them needs.
| Plan item |
What the text sets |
What remains open |
| National blockchain network |
Infrastructure to connect data and economic systems |
Architecture, operator, timeline and budget |
| National computing power network |
Coordination of data centers with the East Data, West Computing program |
How capacity is distributed among provinces |
| Data property rights |
Systems to certify ownership and pilots with data elements |
How conflicts between administrations are resolved |
| Industries of the future |
Quantum technology, biomanufacturing, hydrogen and sixth-generation mobile |
Measurable targets and responsible parties |
Data property rights deserve separate attention. If Beijing manages to certify who owns each piece of data, it will have the basis to treat information as a negotiable economic asset, and blockchain would remain as the layer that verifies that registry. The document itself links the plan to the 15th five-year plan, which covers 2026 to 2030.
From the BSN to a network with unified standards
China has been testing that infrastructure for years. The Blockchain-Based Service Network (BSN) began construction in September 2018 with China Mobile and China UnionPay as partners and was publicly presented on October 15, 2019, although other accounts date it to 2020, a discrepancy that does not change the substance. Building on that experience, a draft dated June 18, 2026 defined the future network as digital infrastructure planned and built under state coordination, with unified technical standards and access rules.
The adjective unified is the piece that decides whether the network is of any use. In a country where provinces and ministries have each built data platforms on their own, the bottleneck is not cryptography or the consensus mechanism: it is getting administrations that do not share formats, identifiers or access criteria to agree. A national network is, above all, a governance problem with a software layer on top.
The draft points to very specific uses, such as distributed digital identities and verifiable credentials for people, organizations, devices and goods. In practice, that describes an identity infrastructure with a public seal, not an open ledger where anyone can write.
The 2021 ban has not moved
It is worth separating two clocks. The infrastructure clock is moving forward, and the market clock has been stopped since September 2021, when Beijing shut down trading and extended the ban to foreign platforms serving clients from the mainland. A notice dated February 6, 2026 again listed what is prohibited: converting yuan into cryptoassets, exchanging one for another, operating as a central counterparty, offering pricing and informational intermediation services, financing token issuances and trading financial products linked to them.
The digital yuan follows its own path, with around 30 banks authorized to offer services with the digital currency. Days before the document was published, Joseph Chee, who led UBS investment banking in Asia and now heads the listed Solana Company, said in an interview that if Beijing finds a way to manage trading and cross-border access, the sector could enter "another supercycle." The interview gave no date, and the 19 measures do not confirm that reading.
Hong Kong plays by another rulebook
The virtual asset path that Hong Kong has been testing for a year runs separately, within the one country, two systems framework. The stablecoin regime the city approved in May 2025 came into force this year, and the bill that will extend licenses to exchanges and custody will reach the Legislative Council in late 2026, as we reviewed in Hong Kong wins the stablecoin race in Asia.
The city's regulatory advantage has an estimated shelf life of about 24 months before Singapore, South Korea and Japan close the gap with their own frameworks and similar liquidity.
Hong Kong can write rules quickly and cannot decide on the currency that backs those rules, because the plan for offshore yuan stablecoins stalled in October 2025 due to capital controls and limited convertibility.
What is already being tested with public money
The useful comparison is not Beijing versus the crypto ecosystem, but Beijing versus the public infrastructures that already exist elsewhere. In Spain, ISBE surpassed 20.3 million euros in public funding in just over three years, went into production in December 2025 and has more than 30 user companies, most of them grant recipients, according to the analysis we published in ISBE, more than 20 million in public funds and doubts about its real use. Public money bought the infrastructure, and adoption is still being measured.
Singapore took the same problem into the realm of money. On October 9, 2026, the same day as the Chinese document, the managing director of the Monetary Authority of Singapore announced that the regulator will settle the tokenized bills issued by the monetary authority itself using wholesale CBDC, as we detailed in Singapore tests bill tokenization with its wholesale CBDC. None of that requires opening the network to permissionless participants; on the contrary, it requires identifying them one by one.
The difference between the three models lies in where the central bank's money lives and who can enter. Europe and Singapore anchor settlement in public money. China additionally adds a filter by identity of people, devices and goods.
If the state operates the network, where does decentralization go?
When the operator is the state and access rules are set by a single standard, what survives of the original promise is the boring and useful part of the technology: shared registries that do not depend on the goodwill of an office, credentials that can be verified without calling anyone and data that a third party can audit. The rest, resistance to censorship and the possibility of participating without asking permission, is left out by design.
For the price of bitcoin, the October 9 document brings no new demand, no access, no legal framework. For everyone else, it leaves a question that Europe will also have to answer when ISBE and Pontes mature: if the infrastructure is operated by the state and identity is a technical requirement to enter, is it still decentralization or is it a shared database with better marketing?